
Disclosure: Commodities Market may earn a commission if you open an account through links on this site. Trading involves risk, and nothing here is personal financial advice.
The soybean crush spread estimates a gross processing margin from turning soybeans into the two products they’re mainly processed into: soybean meal and soybean oil. It’s the agricultural cousin of the oil market’s crack spread. Understanding the soybean crush spread helps explain why soybean, meal and oil prices sometimes move in different directions, and why a bumper bean harvest doesn’t always mean cheap cooking oil. This guide covers how the spread works, how to calculate it, what drives it and how processors and traders use it.
What “crushing” means
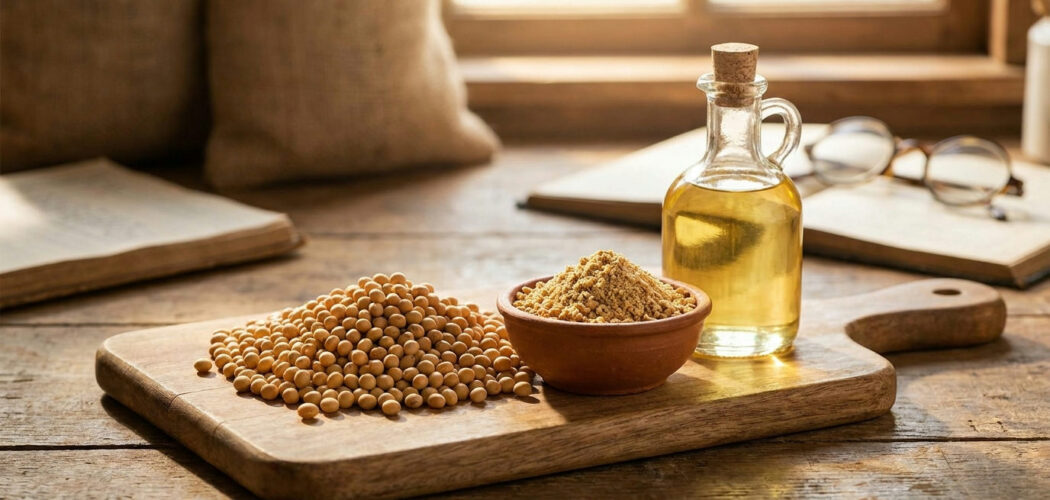
Processors, known as crushers, buy soybeans and crush them to separate two products:
- Soybean meal: a high-protein feed, mainly for poultry, pigs and cattle, and used as a protein ingredient in livestock feed.
- Soybean oil: used in cooking oil, food products and, increasingly, biofuels such as renewable diesel and biodiesel.
A crusher earns money when the combined value of meal and oil exceeds the cost of the soybeans plus processing costs such as energy, labor and plant upkeep. Meal and oil yields differ, but revenue shares depend on both quantities and market prices. A heavier output is not automatically the more valuable one.
How the soybean crush spread is calculated
The crush spread equals the value of meal and oil produced from a bushel of soybeans, minus the price of that bushel. In simple terms:
| Step | What it represents |
|---|---|
| Value of soybean meal from one bushel | Meal price × meal yield per bushel |
| Value of soybean oil from one bushel | Oil price × oil yield per bushel |
| Minus soybean price | Cost of the raw beans |
| Equals the gross crush margin | Before processing costs |
The “board crush” formula
Traders use standard yield assumptions so the calculation stays consistent. The futures-based version, often called the board crush, follows the convention used in CME Group’s grain and oilseed education materials: one bushel of soybeans is assumed to produce roughly 44 pounds of meal and 11 pounds of oil. Since meal futures are quoted per short ton and oil futures in cents per pound, the formula becomes:
Crush ($/bu) = (meal price per ton × 0.022) + (oil price per lb × 11) − soybean price per bushel
The 0.022 converts 44 pounds into a fraction of a 2,000-pound ton. Actual plant yields vary with bean quality, moisture and equipment, so a real crusher’s margin will differ from the board figure, so use the board figure as a standardized comparison rather than a measurement of any particular business.
A simple illustration
Using made-up round numbers purely to show the arithmetic: if meal trades at $300 per ton, oil at 50 cents per pound and soybeans at $11 per bushel, the board crush is (300 × 0.022) + (0.50 × 11) − 11 = 6.60 + 5.50 − 11 = $1.10 per bushel. Processing costs then come out of that $1.10. Change any one price and the margin moves, which is exactly why crushers hedge all three legs.
Separate price changes from explanations
The formula has three price inputs. A higher meal or oil quote raises the calculated spread, while a higher bean quote lowers it, holding the other inputs fixed. Those are arithmetic relationships. Explaining why a quote changed requires additional evidence.
The USDA WASDE report includes oilseed supply-and-use estimates. Start with the report date and marketing year, and distinguish an estimate for beans from one for meal or oil. A change to expected production is different from a change to expected use or ending stocks. Record the specific table and revision you are relying on.
If an explanation involves biofuel rules or incentives, look for the actual dated rule or official announcement, its jurisdiction and effective date. This guide does not establish that any current policy is in force, quantify its effects or assume that an announced proposal will be adopted. A feedstock price alone cannot prove the effect of a policy.
Oil share: a related measure
Traders also watch “oil share,” the portion of the crush value that comes from soybean oil rather than meal. Oil share describes the relative value of the two outputs under the chosen yield assumptions. A rise can come from higher oil prices, lower meal prices or both. It cannot identify fuel demand, food demand or the direction of the next price move by itself.
Who uses the crush spread
- Crushers hedge their margins by buying soybean futures and selling meal and oil futures, to offset changes in planned input and output prices. The hedge does not remove processing costs, local basis differences or quantity mismatch.
- Traders trade the spread itself, betting on margins rather than outright price direction.
- Analysts watch it as a gauge of processing demand for soybeans and of how hard plants are likely to run.
- Livestock producers and food companies follow it to anticipate meal and oil costs.
Write the futures legs explicitly
CME’s soybean-crush lesson distinguishes buying the product legs and selling beans from the opposite combination. A name such as “long crush” can be misunderstood if you do not know which legs it describes. Record each buy or sell, contract month and quantity before interpreting a position.
A processor’s hedge is different from its physical operation. A futures gain may offset a deterioration in the prices relevant to the planned business, while a futures loss can accompany an improvement in those prices. Evaluate the two together. The quoted spread, the processor’s net profit and a futures account’s profit are three different measurements.
Do not turn a per-bushel worksheet directly into a contract order. Each leg has its own contract unit, quote convention, margin requirement and settlement calendar. Consult current specifications and broker terms. The CFTC futures basics warns about losses beyond the initial investment. A spread position still carries price and execution risk.
For more agricultural context, read our guide to agriculture commodities trading. The examples here explain inputs and arithmetic, not a recommendation to take either side of a trade.
Common mistakes when reading the crush
- Treating the board crush as a plant’s actual profit. It is a gross margin before processing costs and before basis differences at the plant’s location.
- Mixing contract months. Compare bean, meal and oil futures for matching delivery periods, and document any deliberately different delivery periods; otherwise you may confuse a calendar effect with a change in processing value.
- Ignoring oil share. Record meal value and oil value separately to see which changed. The total spread alone cannot show whether a change came from feed demand, fuel demand or cheaper beans.
- Forgetting the other oils. A story about another vegetable oil needs evidence about the connection to the soybean quotes being discussed; do not infer it from timing alone.
- Underestimating policy risk. Verify the official text and effective date of any policy claim before using it to explain a price move.
A checklist for following the soybean crush spread
- Pull matching-month soybean, meal and oil futures prices.
- Apply the board crush formula and note the oil share.
- Compare the result with recent months to judge whether margins are wide or narrow.
- Read the relevant dated WASDE tables for revisions to crush, exports and ending stocks.
- Separate published biofuel data from proposals or commentary about policy.
- Watch competing vegetable oil prices, especially palm oil.
Stress-test a hypothetical worksheet
Return to the invented example: meal value is $6.60 per bushel, oil value $5.50, bean cost $11 and the gross spread $1.10. If only bean cost rises by $0.40, the gross spread falls to $0.70. If instead only meal rises by $20 per ton, the meal contribution rises by $20 × 0.022 = $0.44, and the spread becomes $1.54. These are separate hypothetical cases, not current market prices.
Keeping the changes separate shows which input accounts for a result. Add a column for the unit, timestamp and month of each quote. A spreadsheet that mixes cents and dollars can be wrong by a factor of one hundred without producing an obviously broken formula. Check one row by hand before copying the formula down a sheet.
You can also record costs separately. If invented processing and local-price adjustments total $0.90 per bushel, subtracting them from the original $1.10 gross spread leaves $0.20 under those assumptions. That is only an illustrative residual. It does not establish a plant’s actual margin, account for every cost or predict an investable return.
Frequently asked questions
What does a wide crush spread mean?
It means the calculated output value exceeds bean cost by a larger amount under the same assumptions. Whether a particular plant is profitable also depends on its actual yields, local quotes, operating costs and commitments. A wide board spread is not proof of profitability or a promise of mean reversion.
Why has soybean oil become more important?
Soybean oil is one of the two outputs, so a change in its price can affect the calculated spread even when bean and meal quotes are unchanged. Use dated supply-and-use evidence before attributing an observed change to a particular end use.
Is the crush spread like the crack spread?
Yes. Both measure processing margins: the crack spread for refining crude oil into gasoline and distillates, the crush spread for processing soybeans into meal and oil.
The bottom line
The soybean crush spread is the simplest way to see the soybean complex as one connected system. Beans go in, meal and oil come out, and the calculated gap is a gross comparison before local basis and operating costs. Learn the board crush formula, keep an eye on oil share and biofuel policy, and the sometimes puzzling moves in beans, meal and oil start to make sense.
Trading commodities involves risk. Past performance does not guarantee future results. This article is general information, not financial advice.